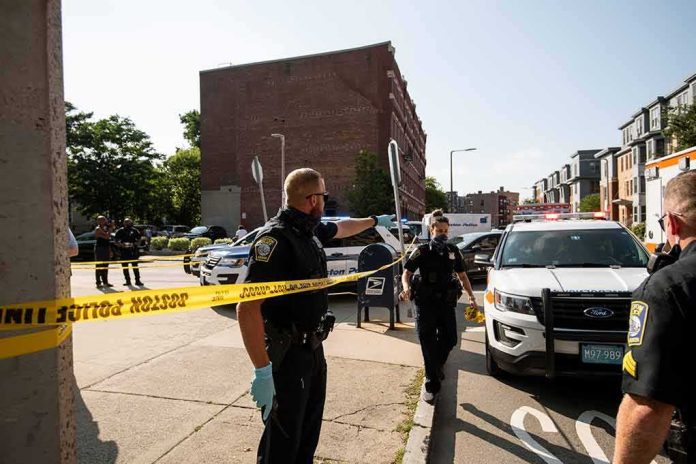
When police damage private property in the course of lawful operations, the financial question is simpler than the legal debates make it appear: a national dataset indicates that writing checks to the people whose doors, windows, and walls were broken would generally cost local governments very little—both in dollars and in administrative lift—relative to most municipal budgets.
The Short Version
- A new national dataset tracks more than 2,700 property-damage claims across 222 jurisdictions, with a median claim of $1,260.
- If every observed claim had been paid, the average jurisdiction would have spent roughly $6,500 per year—orders of magnitude below most public-safety line items.
- Most claims stem from routine residential damage, not rare, high-dollar tactical incidents; typical exposure is small and predictable.
- Many denials rest on immunity and legality, signaling a policy choice not to pay—more than a cost crisis—within current doctrine.
What the dataset actually shows about cost and volume
The Institute for Justice compiled a nationwide review of claims that property owners filed with local governments for damage attributable to law-enforcement activities between 2015 and 2023. Across 222 local jurisdictions, the researchers identified more than 2,700 claims; the median claim amount was $1,260. In a typical year, the average jurisdiction saw one or two such claims, a cadence that keeps administrative burden low. Modeling the simplest fiscal scenario—what if every observed claim were paid—the study estimates an average annual outlay of roughly $6,500 per jurisdiction. That is not an audited spend; it is a straightforward exposure calculation, but as a planning benchmark it is concrete and legible to budget officers weighing tradeoffs in the tens or hundreds of millions.
The composition of loss matters as much as the totals. Most claims involved residential damage tied to routine police work—broken doors on a forced entry, damaged locks, breached windows—rather than outlier events like long standoffs or armored-vehicle entries. Only about 12 percent of claims in the dataset were linked to tactical raids. The heavy middle of the distribution, not the tail, is doing the work here: small, repairable harms to ordinary homes that are inexpensive to make whole and occur at a frequency that is stable enough to budget.
Why so many claims are denied—and why that is a legal story, not a cost story
Governments frequently deny these claims not because they would be ruinously expensive, but because the legal framework often treats police-caused damage during lawful operations as noncompensable. In jurisdictions that follow this view, homeowners cannot recover under the Takings Clause for property damaged as an incident of police power, even when they are innocent third parties. Courts applying emergency or police-power doctrines have repeatedly insulated cities from liability in these circumstances, a line of authority that includes California appellate and Supreme Court decisions. The practical effect is straightforward: claims are rejected on immunity or legality grounds, not because city risk managers fear a budget blowout.
That doctrinal baseline is not universal. Some state constitutions and courts have taken a different path. The Texas Supreme Court, for example, has held that cities must compensate owners for certain police-caused damage under the Texas Constitution. Legislatures have also authorized local reimbursement programs for “innocent residents,” which function as policy carve-outs where doctrine would otherwise bar recovery. These counterexamples prove the core point: whether victims are paid is primarily a rule-of-law decision that cities and states can change; the dollars involved, on average, are modest.
Mechanics: how reimbursement would work in the real world
From a municipal risk-management perspective, there are three moving parts: claims intake, valuation, and funding. The intake is familiar—cities already process third-party property claims arising from everything from pothole damage to utility mishaps. Valuation can follow ordinary repair or replacement-cost principles used in restitution and civil claims: invoices for labor and materials, reasonable market pricing for doors, windows, locks, drywall, and paint, and documentation of ancillary costs like boarding and security. Many DA-led victim restitution programs already handle property-damage assessments in criminal cases; the administrative know-how to price losses is not exotic.
Funding options are similarly standard. Self-insured retention can absorb routine claims; pooled risk or insurance can be retained for the small tail of larger incidents. Because the observed claim volume per jurisdiction is typically one or two per year and the median dollar figure is low, most cities could manage this as a predictable operating expense, analogous to sidewalk trip claims. Where policymakers fear moral hazard—concern that reimbursement dulls incentives to minimize damage—eligibility criteria can require that police actions be lawful and reasonable while still making innocent owners whole. The dataset’s small-dollar center suggests this would not require new bureaucracies; it would require a policy decision to pay.
Police officers sometimes damage or destroy innocent people's property. More often than not, they refuse to reimburse for the damage. https://t.co/24HmTIfVXm
— reason (@reason) September 15, 2026
Limitations: what the current evidence can and cannot prove
Any responsible reading of the dataset must acknowledge its boundaries. The 2,700-plus claims are those the researchers could identify through public-records processes across 222 jurisdictions; it is not a census of all police-caused damage nationwide. Not every victim files a claim, and not every agency maintains searchable, complete logs. The $6,500 figure is a modeled average exposure based on observed claims, not a historical expenditure line, and it does not include potential litigation or overhead. Finally, the study’s top-line summary blends resolved and unresolved claims, and it does not disaggregate costs by operation type in a way that would yield separate curves for routine entries versus rare, catastrophic events. These are solvable with fuller data publication and independent replication; they do not, however, transform a low, stable median into a high, volatile risk.
Context: accountability, indemnification, and the real locus of choice
This debate sits inside a broader pattern in American policing finance: governments, not individual officers, bear almost all monetary consequences for on-the-job harms. In civil-rights litigation, for instance, empirical work shows governments pay essentially all dollars recovered—near-total indemnification in practice. That history should temper fears that reimbursement would create a novel fiscal exposure; the question is how to align routine, small property losses with the public entities already structured to pay. Consider the optics and equity, too. Most residents cannot afford to self-insure a splintered front door or a shattered bay window. When the damage is a predictable byproduct of public safety delivered for everyone’s benefit, socializing that narrow cost through the city ledger is both administratively tidy and civically coherent.
Policy path forward: make the small stuff right, keep the hard stuff hard
Policymakers do not need to resolve the Takings Clause for every edge case to fix the center of the distribution. A practical blueprint is available now: adopt local ordinances or state statutes that (1) create a streamlined administrative remedy for innocent owners whose property was reasonably damaged during lawful operations; (2) set clear documentation standards and valuation rules anchored in repair and replacement cost; (3) fund payments from existing risk pools with periodic public reporting; and (4) preserve separate litigation channels for rare, high-dollar disputes. Jurisdictions with existing victim-restitution infrastructure can adapt those processes; where doctrine bars recovery, legislatures can authorize programs without conceding constitutional questions. The evidence to date supports a simple judgment: paying these small, routine claims is affordable, manageable, and fair.
Sources:
reason.com, yahoo.com, ij.org, ojp.gov, da.lacounty.gov, cityprosecutordoughaubert.com, scholarship.law.wm.edu